Not every stock caught in a market-wide selloff deserves to be there, and Jim Cramer thinks investors are lumping one particular chipmaker in with names it does not really belong next to. His argument arrived in the middle of a genuinely rough time for AI stocks broadly, which made the timing of his pitch nearly impossible to ignore.
The backdrop was not subtle in the slightest. AI-related shares were getting hit hard across the board that day. Cramer used the moment to point out that panic selling and genuine business deterioration are two very different things, which markets frequently confuse.
Cramer says Broadcom is too cheap to be ignored
Cramer addressed the broader tech pullback during the September 14 episode of Mad Money, framing the day’s carnage around growing caution from two of the industry’s biggest names. “It’s a tough time to come out to San Francisco, a day when the whole AI complex is getting hammered because Anthropic and OpenAI seem to be, I don’t know, pulling in their horns,” he said.
Rather than treating the selloff as a reason to retreat, Cramer pointed to it as an opportunity. “Actually, I think there’s some real bargains in this group,” he said, singling out Broadcom, the chipmaker behind custom silicon, networking equipment and infrastructure software, whose stock had fallen more than 10% over the past month.
More Jim Cramer:
- Jim Cramer has terrifying one-word message for tech stock investors
- Jim Cramer says he’s steering clear of one popular stock
- Jim Cramer reveals 4 surging chip stocks he likes best
Cramer walked through why the drop looked overdone to him. Broadcom had reported strong third quarter results in early September and issued what he called a spectacular multi-year forecast, but the guidance for the current quarter struck some investors as merely in line rather than blowout, triggering the pullback.
His closing argument leaned on the company’s track record. “I think Broadcom’s still on track to put up some incredible growth because they’re at the heart of the AI ecosystem, because the company’s never let us down in all the years my Charitable Trust has owned it,” Cramer said, noting the stock sat roughly 150 points below its June high and calling it “too cheap to ignore.”
The financial case behind Broadcom
The numbers behind Cramer’s confidence are substantial. Broadcom’s fiscal third-quarter revenue reached $29.6 billion, an 86% jump from the same period a year earlier, while AI semiconductor revenue surged 221% to $16.7 billion, now accounting for roughly 56% of total revenue, TheStreet reported.
Broadcom’s backlog gives that growth real staying power. Remaining performance obligations climbed to $179.2 billion, providing investors with substantial visibility into revenue the company has already locked in but has not yet recognized.
Management is not projecting a slowdown. Fourth-quarter guidance calls for AI semiconductor revenue of $21.7 billion, up 236% year over year, alongside consolidated revenue of $34.8 billion, pushing full fiscal 2026 AI revenue guidance up to $58 billion from a prior forecast of $56 billion, according to TheStreet.
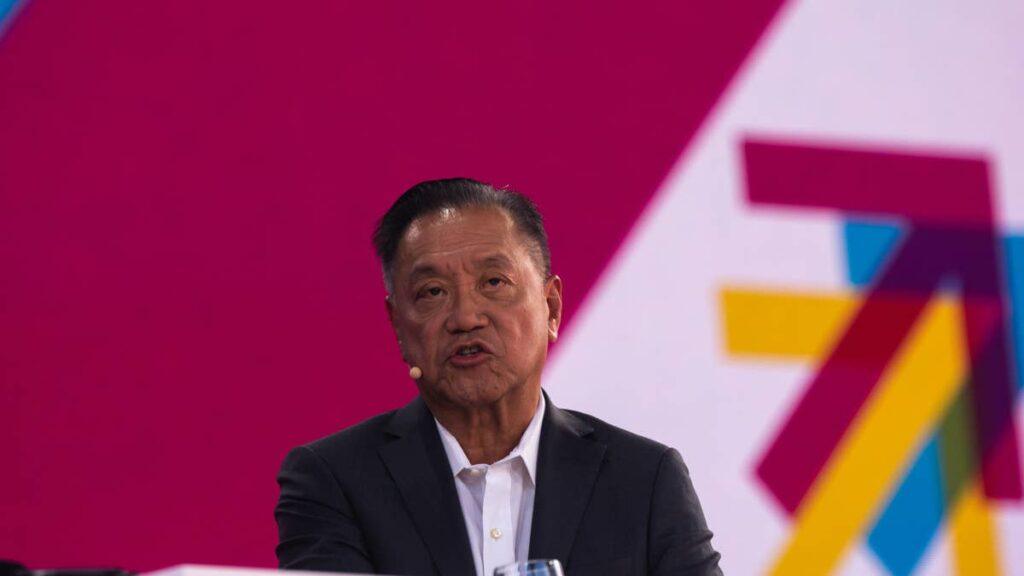
The multi-year targets go even further. CEO Hock Tan guided fiscal 2027 AI semiconductor revenue to approximately $115 billion, roughly doubling again to $230 billion in fiscal 2028, with major hyperscale customers including Alphabet, Meta, Anthropic and OpenAI anchoring that growth trajectory.
NurPhoto / Getty Images
Weighing valuation realities
Even with those record results, the market reacted sharply once near-term guidance failed to match the explosive beats investors had grown accustomed to. Broadcom shares had dropped roughly 7% from their September 2 closing price following the earnings report, pushing the forward earnings multiple down to 18.1 times, according to Insider Monkey.
Truist cut its price target but kept the buy. The reason it stayed bullish was the same reason Cramer stayed bullish. $230 billion in AI revenue by fiscal 2028 does not get revised away by one quarter of in-line guidance.
Other firms remain considerably more aggressive. Morgan Stanley raised its price target to $505 following the results, with the average analyst target across 29 firms sitting near $518, implying roughly 45% upside from current levels even after the post-earnings pullback, TheStreet reported.
Hock Tan addressed the broader AI slowdown narrative directly on the same September 14 episode of Mad Money. He told viewers that nothing in the Anthropic-driven caution changes Broadcom’s own forecasts, reinforcing Cramer’s argument that the selloff reflects sentiment rather than fundamentals, as reported by CNBC.
What institutional investors are watching
The big institutions are not running. 170 hedge funds held Broadcom in the second quarter, down slightly from 173 the prior quarter. Fisher Asset Management was the largest holder at 15.1 million shares, according to Insider Monkey. Three fewer funds. Not a stampede.
History offers a cautionary parallel worth remembering. Similar guidance-driven selloffs have hit other AI bellwethers like Nvidia, Marvell and Arista Networks this year after merely in-line quarters followed periods of parabolic gains. In several cases, subsequent results showing that underlying AI demand remained strong helped ease those concerns.
Whether Broadcom’s current dip proves to be the buying opportunity Cramer describes will likely hinge on execution against those ambitious multi-year AI targets rather than any single quarter’s guidance falling short of lofty expectations. For now, a compressed valuation paired with a backlog stretching years into the future gives his case considerably more substance than a simple contrarian call typically carries.
Related: Broadcom CEO delivers blunt verdict on AI’s biggest debate right now