During the Lightning Round of the Oct. 1 episode of “Mad Money,” Jim Cramer told viewers he was ready to buy more Kimberly-Clark (KMB).
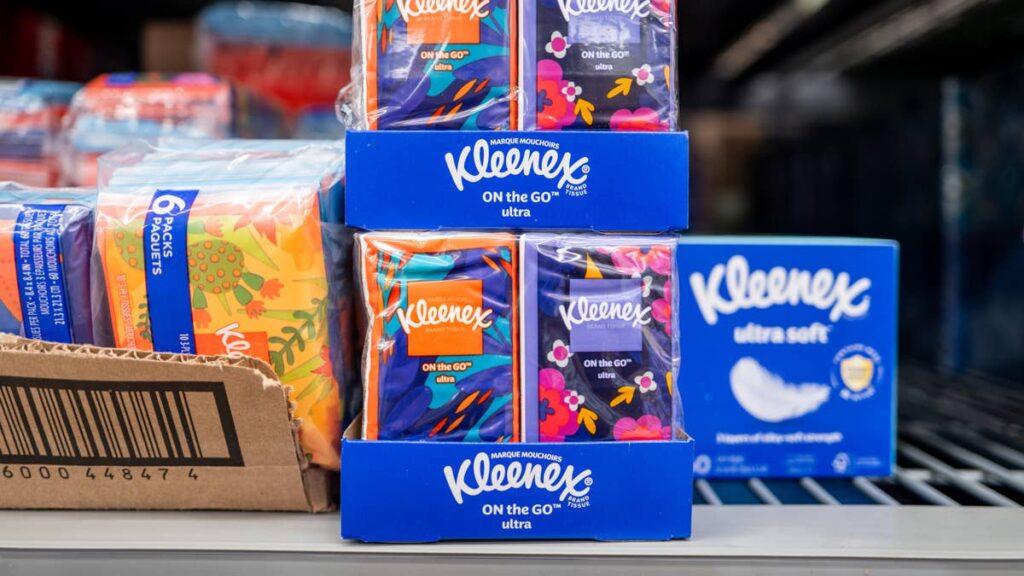
Kimberly-Clark is the company that makes some of the regular household products we use, such as Kleenex tissues and Scott paper towels. However, the stock hasn’t been doing all that great recently.
KMB’s value has dropped by about 20% over the past year for several reasons, including investor uncertainty about the company’s pending acquisition deal with Kenvue. That’s why Cramer’s call is worth noting.
Kimberly-Clark’s acquisition of Kenvue (KVUE) is a blockbuster $48.7 billion consumer staples consolidation, designed to build a $32 billion global health and wellness giant capable of going toe-to-toe with sector leader Procter & Gamble.
Cramer has hosted “Mad Money” since 2005, and he also runs the CNBC Investing Club with Jeff Marks, so many investors value his opinion.
But this time, his view is quite different from how many Wall Street analysts see KMB stock.
Cramer tells viewers Kimberly-Clark is a buy in the $90s
When a viewer called and asked about the stock, Cramer said, “One, I think it’s a buy, and two, when I talk about it with Jeff Marks, I feel I started too soon. It’s become a bond play, but I am going to buy more because I think the combination with Kenvue is unstoppable.”
Also read: Jim Cramer noticed something odd about the stock market
For him to use the word “unstoppable,” that means he has a certain level of confidence in the stock. He even supported the statement, saying, “I am willing to stick my neck out and say I’m not going to regret buying Kimberly-Clark in the $90s a few years from now.”
Kimberly-Clark recently raised its quarterly dividend to $1.28 per share, which gives the stock a yield of about 5.4%.
Brandon Bell / Getty Images
Why Kimberly-Clark stock keeps falling near a 52-week low
You can find Kimberly-Clark products in many grocery stores around the country. It is the company behind popular brands including Huggies, Kleenex, Cottonelle, Scott, and Kotex. Each of those businesses usually brings in steady profits, but 2026 has been a bit rough.
KMB closed at $94.36 on Oct. 2 and was down about 7% year to date at the time. In fact, the stock is quite close to a 52-week low of $92.42.
Related: Jim Cramer delivers unmistakable verdict on AMD’s future after 281% run
The stock fell mainly because of a six-alarm arson fire at a major 1.2 million-square-foot U.S. distribution center and a mid-September profit warning resulting from the company’s delays in launching new products.
At a range of about 13 to 14 times forward earnings, KMB now trades at its cheapest valuation in 10 years. Analysts at Simply Wall St wrote that the stock “still looks cheap despite a 16% slump” when compared with its fair value.
The Kenvue deal is the real reason behind Cramer’s bullish call
One of the main reasons why Cramer is still bullish on KMB is its pending deal with Kenvue. Kenvue was formerly a part of Johnson & Johnson’s consumer health division, and it makes Tylenol, Band-Aid, Neutrogena, and Listerine.
KMB shareholders approved the deal earlier this year, and Kimberly-Clark reported that 96% of them supported it.
More Jim Cramer Coverage:
- Jim Cramer issues blunt warning on high-dividend stocks
- Cramer sends unmistakable verdict on BlackBerry before earnings
- Cramer pours cold water on Rocket Companies before earnings
Once the deal closes in the second half of 2026 under CEO Mike Hsu, Kimberly-Clark will be able to add high-profit personal health products to its lineup.
Cramer believes that with the new deal, KMB could become a serious rival for Procter & Gamble, which is the top name when it comes to household goods.
What everyday investors should consider before buying KMB
Although Cramer sounds confident about KMB, the stock still carries some risks.
For one thing, investors still need to wait for the Nov. 3 third-quarter earnings report to know whether the warehouse fire problems are no longer affecting the company. If not, the stock could fall again.
The merger with Kenvue is another consideration. Large deals like this often take time before delivering the profit people expect. So if you’re buying today, you should be ready to hold the stock for at least a full year before expecting substantial gains.
A high dividend yield alone is usually not enough reason to buy a stock, but KMB has something many peers don’t have. The company has increased its dividend for 54 straight years, which makes it qualify as a Dividend King.
Also, some investors feel its 5.4% yield is worthwhile enough for them to wait while the company completes the Kenvue merger.
More Stocks News
- Morgan Stanley revisits Micron stock price target amid stellar growth
- Goldman Sachs resets Nike stock price target after brand disappoints
- Warren Buffett’s farewell letter has 4 words for every investor
- Stock Market Today (Oct. 5, 2026): S&P 500 moves higher, yields higher after payrolls data