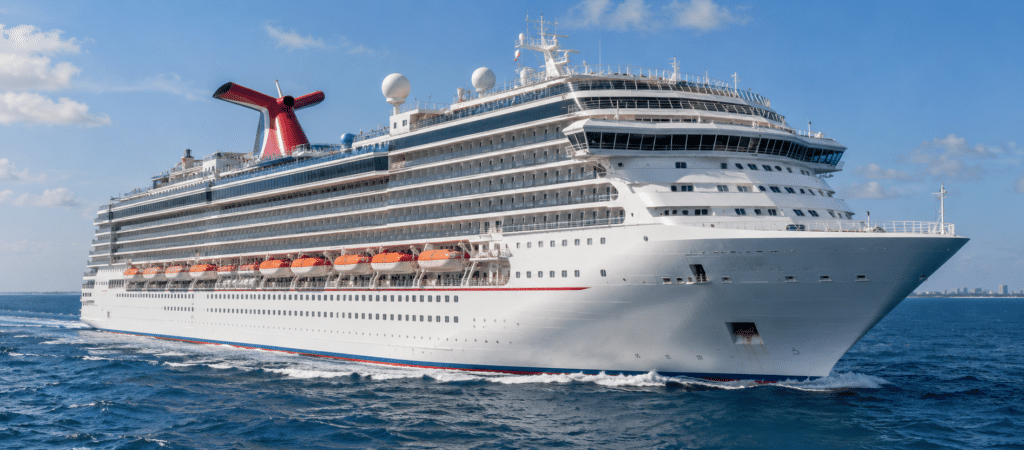
Carnival (CCL) delivered a blockbuster Q3 earnings report today, outperforming guidance with an all-time high net income of $1.9 billion and record revenues of $8.44 billion.
While investors celebrated the top-line beat, the “real race” for CFO David Bernstein is happening on the balance sheet.
The cruise firm is using its huge operational wave to race against a lingering mountain of pandemic-era debt.
For CCL, every dollar of current free cash flow serves as critical leverage to chip away at higher-interest maturities before costly refinancing terms take hold.
As of writing, Carnival stock is down some 15% year-to-date.
What the debt mountain means for Carnival stock
During the global cruise shutdown, Carnival Corp was forced to take on high-yield, expensive debt to keep its fleet afloat.
Today’s quarterly print confirms that the company is converting record passenger yields and strong onboard spending directly into balance sheet repair.
Net interest expense for the quarter landed at $260 million, but the long-term goal remains aggressive debt retirement.
As legacy low-rate tranches reach maturity over the coming quarters, Carnival is attempting to pay down principal outright using organic cash rather than refinancing at current market yields.
By shrinking its net debt exposure now, management is shielding future net income margins from persistent macroeconomic interest rate pressures, which may help CCL shares push further up over time.
Free cash flow vs. heavy fleet expenditures
Despite delivering an impressive $2 billion in adjusted net income for Q3, CCL’s cash conversion faces a continuous tug-of-war against capital demands.
Cruise operations require continuous reinvestment: fourth-quarter capital expenditures alone are projected at $1.2 billion across newbuilds and fleet upgrades.
Moreover, external operational pressures, including volatile fuel prices and elevated voyage costs, continue to bite into liquid margins.
Generating sufficient free cash flow means Carnival Corp must maintain peak occupancy and firm ticket pricing while simultaneously absorbing heavy maintenance outlay.
If booking momentum softens or cost inflation accelerates, the pace of debt reduction could slow, leaving Carnival shares exposed to costlier debt rollovers down the line.
CCL shares’ derisking horizon and long-term value
Carnival’s full-year 2026 adjusted EBITDA projection of about $7.14 billion highlights a structural turnaround from survival mode to sustained cash generation.
Strong advance bookings stretching into 2027 offer crucial cash visibility – allowing management to methodically prepay debt notes and improve the firm’s overall credit profile.
If Carnival Corp continues on this trajectory, it will successfully cross its debt wall without diluting shareholders or sacrificing fleet modernizations.
For Wall Street, today’s rally is less about a single quarter’s earnings beat and more about whether CCL stock can permanently de-risk its enterprise value.
In the post-crisis cruise sector, cash flow isn’t just funding growth – it is buying financial freedom.
The post Carnival's debt wall sprint: can record profits beat higher rates? appeared first on Invezz