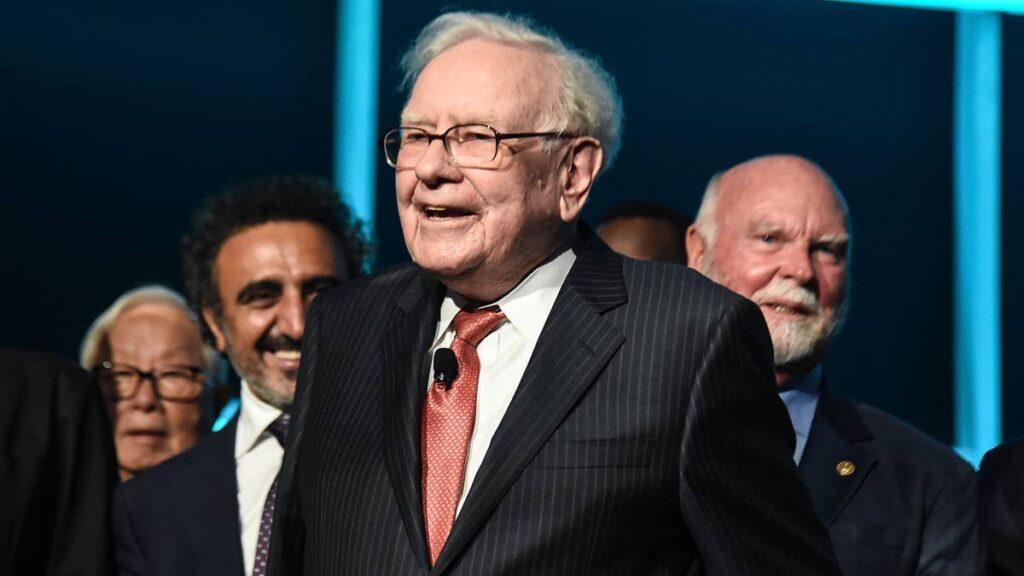
Warren Buffett ran Berkshire Hathaway for more than six decades.
When his farewell letter came out, the coverage went straight to the succession plan, the handoff to Greg Abel, what the company looks like going forward without him.
Most of that coverage missed the part that mattered most to individual investors. It was four words, buried in a letter full of business news, and it was not complicated.
He had been writing shareholder letters since 1965. Nearly every one of them made some version of the same argument about time and patience and not selling when markets fall. TheStreet reported on the significance of Buffett going quiet, but the investment message in the farewell letter is what most people reading it could actually use.
He said it plainly. At 96, there was no next letter to save it for.
The letter covered a lot of ground. Succession, philanthropy, the partnership with the late Charlie Munger. But there was one section investors kept coming back to.
Buffett had circled the subject of Father Time before. In the farewell letter itself, he put it directly: Father Time “is undefeated; for him, everyone ends up on his score card as ‘wins.'” For the investors who read past the business headlines, those words pointed somewhere useful.
Also read: Warren Buffett doubles down on stock market message for 2026
The four words Buffett left behind
“Father Time always wins.”
Buffett was not writing a meditation on aging. He was making a narrower point about what time does for an investor who gets out of its way.
Holding a broad market index through crashes and recoveries without selling is not a sophisticated strategy. It just requires staying in the account while most people do not.
He has made this argument in different forms across decades. At shareholder meetings using hypothetical portfolios. In interviews using his own early investment history. In letters laying out the compounding math over 30 and 40-year windows.
The farewell letter did not add anything new to the philosophy. It just said it more directly than anything that came before, probably because there was no next time to say it.
The S&P 500 has returned roughly 11.5% annually over the past four decades, dividends included. Buffett has said future returns may come in lower and he has not backed away from that.
He said it in 2023 and said it again before stepping back. The letter does not promise anything about what markets will do. The argument is about behavior, not return forecasts.
Daniel Zuchnik / Getty Images
Why Buffett kept pointing people toward index funds
In his 2013 letter to Berkshire shareholders, Buffett said 90% of the money set aside in trust for his wife should go into a low-cost S&P 500 index fund. He named Vanguard.
The Vanguard S&P 500 ETF carries an expense ratio of 0.03%. The difference between that and paying 1% a year in management fees compounds for 40 years. It is not a small number.
According to S&P Global’s SPIVA, 86% of actively managed large-cap funds underperformed the S&P 500 over the past ten years.
Buffett put money on this. He bet a hedge fund manager a million dollars that the S&P 500 would beat a basket of hedge funds over a decade. The bet ended in 2017. The index returned roughly 125%. The hedge funds averaged roughly 24%.
His point was never that fund managers are bad at their jobs. Fees are the problem.
Most skilled managers cannot outrun the drag of annual costs compounding against their returns, no matter how well they pick stocks.
Buffett did not invent the index fund. John Bogle did, and Buffett has said so on the record. Spending five decades as the most famous active investor in the country and then telling ordinary people not to try it is what made his position unusual.
What the numbers look like over a long enough stretch
Put $20,000 into a broad index fund and leave it untouched for 40 years at that 11.5% historical average and you end up close to $1.5 million. Add $1,000 a month in contributions over the same period and the number approaches $10 million.
Neither projection means much without the thing that actually produces them: not selling. The year that wrecks a multi-decade compounding run is rarely the year the market crashes. It is usually the year the investor decides to wait in cash until things settle down.
More Warren Buffett:
- Warren Buffett reveals he broke his own investing pattern
- Warren Buffett has a blunt take on today’s market
- Warren Buffett pulls no punches on stock market for 2026
Dollar-cost averaging is buying a fixed dollar amount on a regular schedule no matter what the market is doing. When prices fall, the same dollar buys more shares. When they rise, it buys fewer. That is the mechanics of it.
What it actually takes to do it is continuing to buy when every piece of financial news is making the case for stopping. Most investors who sell into a downturn to wait for clarity end up getting back in at higher prices than the ones they left at.
The 11.5% historical figure is gross. Pull out inflation running around 3% and a 1% annual expense ratio and the real after-cost return is closer to 7%. Seven percent over 40 years is still a meaningful number.
But projections built on the gross figure and projections built on what you actually keep are not the same projection. The gap between them grows with every decade. Someone planning on one and living on the other will notice eventually.
What made the farewell letter different from everything else he wrote
Buffett wrote to Berkshire shareholders every year for six decades. The letters ran long and covered everything from capital allocation to why he thought most Wall Street compensation was absurd. The final lesson before he stepped down carried weight that a mid-career letter from the same person would not.
A fund manager telling retail investors to stop trying to beat the market has an obvious interest in saying it. Buffett spent five decades at the top of active investing and then said the same thing.
He built the career that most people in finance would want and used it to argue that ordinary investors should not attempt what he did. Nobody else making that argument was making it from the same place.
The farewell letter was not long. It was not a summary of six decades of investment thinking and not trying to be. Buffett had said the important things many times and did not see a need to restate them at the end.
The Father Time section is easy to scroll past in a letter full of news about succession and philanthropy. For anyone who stops at it, the investment instruction underneath is the same one he kept repeating throughout his career. Buy broadly. Keep costs low. Give it time. Leave it alone while it works.
Related: Warren Buffett has a stark message for stock market investors